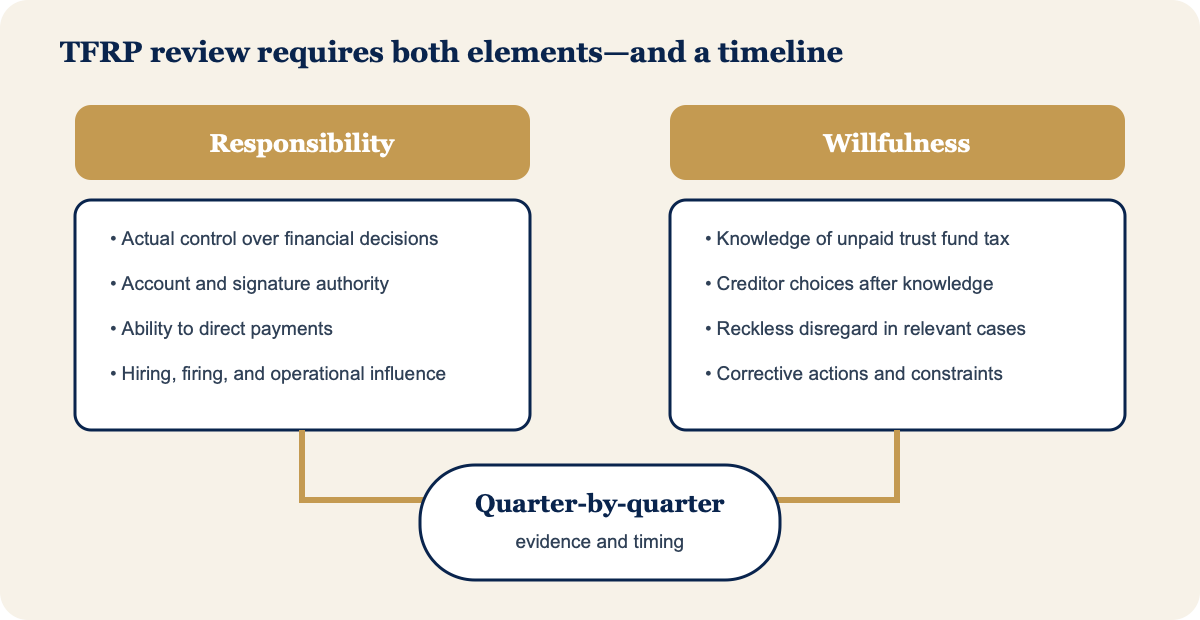
The Trust Fund Recovery Penalty can make responsible and willful individuals personally liable for the trust-fund portion of unpaid employment taxes. Job title alone is not decisive; actual authority, knowledge, and financial decisions matter.
Why this question matters
Employment tax cases combine business records, deposit rules, worker classification, and possible personal exposure. Current compliance and quarter-by-quarter analysis are essential.
The correct response is specific to the taxpayer, tax period, notice, procedural history, and current agency rules. Do not use a general web article as a substitute for reading the actual notice or obtaining advice about a deadline.
A practical framework
1. Obtain payroll returns, transcripts, bank records, and signature-authority documents
Start with the record rather than assumptions. Obtain payroll returns, transcripts, bank records, and signature-authority documents.
2. Map who controlled funds and creditor payments during each quarter
Connect each fact to a document and tax period. Map who controlled funds and creditor payments during each quarter.
3. Build a timeline of knowledge about the delinquency
Consistency matters across forms, transcripts, and agency communications. Build a timeline of knowledge about the delinquency.
4. Respond carefully to interviews and proposed assessment notices
Before submission, check the current form, address, delivery method, and deadline. Respond carefully to interviews and proposed assessment notices.
Documents to gather
- Forms 941 and payroll registers
- Deposit confirmations and bank statements
- Signature and authority records
- Quarter-by-quarter account transcripts
Organize copies in chronological order and keep the originals secure. A short index showing the date, source, tax period, and purpose of each item can make agency review more efficient.
Common mistakes
- Assuming only an owner can be assessed. This can weaken the factual record, consume a procedural deadline, or lead the agency to evaluate an option that does not fit the case.
- Treating every employee with check-signing authority as automatically liable. This can weaken the factual record, consume a procedural deadline, or lead the agency to evaluate an option that does not fit the case.
- Paying other creditors after learning withheld taxes were unpaid without analyzing willfulness. This can weaken the factual record, consume a procedural deadline, or lead the agency to evaluate an option that does not fit the case.
When legal representation may help
Representation becomes more important when enforcement is active, several years or agencies are involved, the liability is disputed, records are incomplete, a business or third party may be exposed, or statements could have civil or criminal consequences. A sound engagement defines the problem, the work to be performed, who will perform it, the fee terms, and realistic objectives without guaranteeing a result.
Frequently asked questions
Is the penalty the entire employer tax balance?
It generally targets the trust-fund component, but the exact computation must be reviewed by period.
Can more than one person be assessed?
Yes. The IRS can assess multiple persons when it finds the requirements met, while collecting no more than the total recoverable amount.
Visual guide
Primary sources
- IRS — Employment Taxes and the Trust Fund Recovery Penalty
- IRS Manual — Responsibility and Willfulness for TFRP
Sources were accessed for editorial research on 2026-08-12. Agency pages, forms, thresholds, and procedures can change; verify the current version before publication and before acting.
Important notice
This article provides general information, not legal or tax advice. It does not create an attorney-client relationship. Outcomes depend on individual facts and current law.